
Avoid MEC Risk in 7 Years: CVAT vs GPT for U.S. Entrepreneurs

COMPLIANCE NOTE: For educational purposes only. Not financial, tax, or legal advice.
CVAT limits how much cash value a policy can hold relative to its net single premium. GPT instead caps cumulative premiums and enforces a death benefit corridor. Both satisfy IRC §7702, but the insurer locks in one test at issue, and that single decision shapes funding flexibility and death benefit behavior for the life of the contract.
TL;DR:
CVAT allows flexible premium payments but triggers automatic death benefit increases whenever cash value exceeds the net single premium ceiling.
GPT restricts total premiums paid and maintains a death benefit to cash value corridor that widens with age, fostering steadier policy behavior.
The net single premium under CVAT is recalculated whenever cash value nears the ceiling, potentially raising death benefits without additional premiums.
For policies using GPT, a higher assumed interest rate shrinks the guideline single premium, limiting lump-sum deposits and reducing early funding volatility.
Advisors should request interest, mortality, and corridor assumptions from carriers and run parallel illustrations to validate the policy’s compliance and suitability for client goals.
Table of Contents
CVAT vs GPT: Comparing Limits and Triggers
CVAT and GPT solve the same regulatory problem in different ways. Both exist so a life insurance contract does not become a disguised investment account, but they restrict different variables.
CVAT caps cash surrender value. The value cannot exceed the net single premium needed to fund future benefits at that point in the contract. When cash value creeps toward that ceiling, the death benefit rises automatically to restore compliance, which is why CVAT-based policies can show a stair-step death benefit pattern over time, according to Investopedia’s CVAT explainer.
GPT caps premiums, not cash value. It uses a guideline single premium and a guideline level premium to set the ceiling on how much can go into the policy cumulatively. GPT also imposes a corridor: a minimum ratio between death benefit and cash value that widens as the insured ages, per Investopedia’s GPT explainer.
Key operational differences:
CVAT allows unlimited premium flexibility but restricts how much cash can accumulate before the death benefit must increase.
GPT restricts total premium inflow but generally produces steadier death benefit behavior once the corridor is set.
Both tests trigger recalculation when death benefit or cash value changes, and both use attained-age tables to reset limits.
Only CVAT forces an automatic death benefit bump; GPT relies on the corridor ratio instead.
Every dollar of cash value above the CVAT ceiling forces a death benefit increase, which raises the cost of insurance the client pays going forward. That single mechanical fact is often the deciding factor for advisors comparing illustrations side by side.
The Math Behind Net Single Premium and the GPT Corridor
Every test rests on an actuarial calculation the carrier runs behind the scenes, and advisors reviewing an illustration should understand what feeds it.
Under CVAT, the net single premium is the theoretical lump sum needed today, at a stated interest and mortality assumption, to fund all future benefits. The insurer recalculates this figure whenever cash value approaches the ceiling, which is why a CVAT policy’s death benefit can rise even without additional premium.
GPT works differently. The guideline single premium uses a higher assumed interest rate than the guideline level premium, which intentionally shrinks the dollar amount a client could dump into the policy as a single deposit, an intentional design choice noted in §7702’s legislative framework. Historically, statutory caps were set for the guideline single premium and guideline level premium, though post-2020 rules replaced those fixed figures with a floating mechanic described below. The corridor percentage itself scales by attained age, requiring a larger death-benefit cushion over cash value for younger insureds than for those in their 80s.
Before signing off on any illustration, request these specifics from the carrier or actuary:
The interest rate assumption used for both net single premium and guideline premium calculations.
The mortality basis (often a standard CSO table) applied to the corridor.
Expense assumptions baked into the illustrated cost of insurance.
The corridor table showing minimum death-benefit percentages by attained age.
Funding Strategy, MEC Exposure, and Loan Mechanics
CVAT and GPT each shape how a client can fund a policy, and both interact with a separate rule that can override the benefit of either test — for detailed estate and insurance planning, see services at Golden Memorial.
CVAT favors large, front-loaded funding. A client depositing substantial capital early can do so without hitting a premium ceiling, but that same funding pattern pushes cash value toward the CVAT limit faster, triggering the automatic death benefit increases described earlier and raising cost of insurance over time.
GPT favors steadier, long-term funding. Because premiums are capped rather than cash value, GPT-based designs tend to show less death benefit volatility, which many advisors prefer for retirement-accumulation strategies according to LegalClarity’s comparison of the two tests.
The 7-pay test runs independently of both. Regardless of whether a policy uses CVAT or GPT, funding it too aggressively in the first seven years can trigger Modified Endowment Contract status, which changes how loans and withdrawals are taxed. Advisors should always run 7-pay projections alongside CVAT or GPT illustrations. The Infinite Banker’s guide to beating the 7-pay test walks through how entrepreneurs structure high early funding without crossing that line, and the companion piece on avoiding MEC status covers the penalty mechanics in more detail.
Policy loans behave the same under either test. Loan balances accrue interest, and unpaid interest and principal reduce both cash value and death benefit. A policy funded aggressively, then leaned on heavily for loans, can lapse faster than expected if the loan balance is never addressed.
Pro Tip: Always ask the illustration software to run a “loan repayment scenario” alongside the standard illustration. Seeing cash value and death benefit net of an unpaid loan balance over 10, 20, and 30 years tells you far more than the base illustration alone.
How to Choose Between CVAT and GPT for a Given Client
Selecting a test is not something the client typically controls directly. The carrier and product design determine which test governs a given contract, but understanding client goals still shapes which carrier and product to recommend.
Decision factors worth walking through with a client:
Funding timeline: does the client want to deposit a large sum early, or fund steadily over years?
Tolerance for death benefit drift, since CVAT policies can see the death benefit rise without added premium.
Intended use of the policy, whether that is income replacement, liquidity for real estate deals, or an Infinite Banking style cash access strategy.
Comfort with premium ceilings, since GPT restricts cumulative deposits more than CVAT does.
When reviewing carrier proposals, ask these questions directly:
Which §7702 test governs this contract, and is that disclosed in the actuarial memo?
What interest rate and mortality assumptions feed the illustration?
What corridor table applies, and how does it change by attained age?
Does the illustration include 7-pay and MEC projections alongside the base numbers?
Red flags include a missing actuarial memo, unusually optimistic interest assumptions that inflate illustrated cash value, or any carrier that cannot produce a clear MEC disclosure. The safest next step is running parallel illustrations under both frameworks before committing to a design, and documenting every assumption used.
What Changed After 2020 in the §7702 Interest Rate Rules
The Consolidated Appropriations Act, 2021 replaced the old fixed statutory interest rates (6% for guideline single premium calculations, 4% for guideline level premium and CVAT calculations) with a floating mechanic tied to the NAIC prescribed valuation rate or a 60-month federal mid-term average, with transitional floors set for 2021.
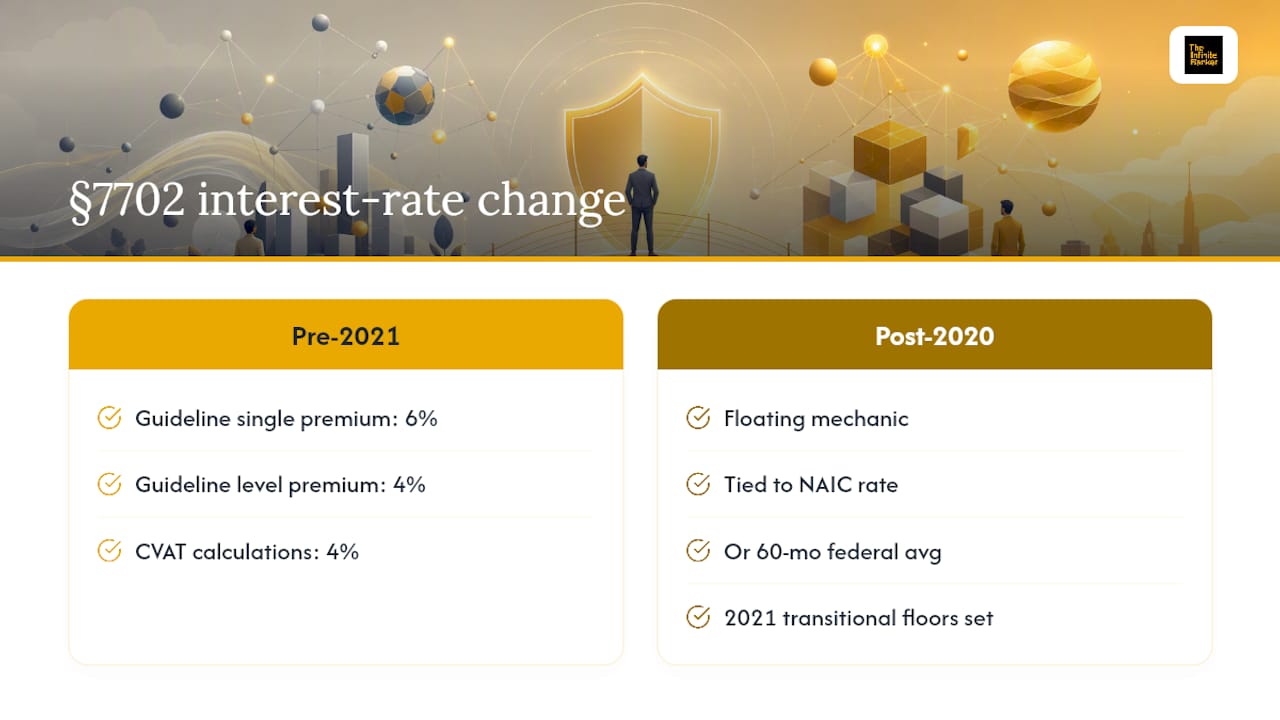
Whether that works in a client’s favor depends entirely on which rate the carrier applies and how recently the policy was issued.
An Advisor’s Take on Choosing the Right Test
The trade-off comes down to funding style, not which test is inherently “better.” Clients with a lump sum to deposit often gravitate toward CVAT’s flexibility, while clients who prefer steady, predictable funding tend to see less death benefit volatility under GPT. In Infinite Banking-style whole life planning, steadier GPT designs frequently align well with clients building long-term cash access, though CVAT can still suit high earners with irregular capital events. Document every assumption, run parallel illustrations under both frameworks, and review the design with an Authorized IBC Practitioner before finalizing a strategy.
— Jib Hunt
Where to Verify These Rules Yourself
Confirm any test detail directly against 26 U.S. Code §7702, IRS technical guidance, or an actuarial memo before relying on any illustration.
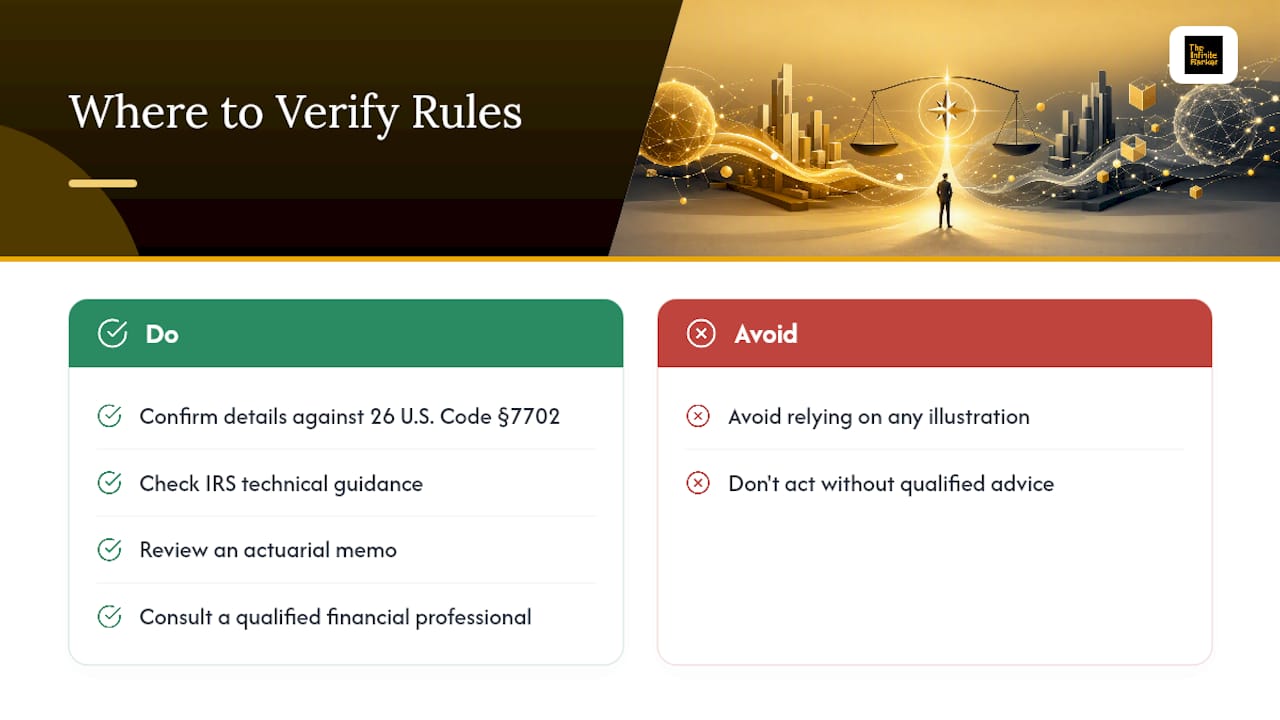
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
FAQ
What is the difference between GPT and CVAT?
CVAT limits how much cash surrender value a policy can hold relative to its net single premium, while GPT caps cumulative premiums through guideline single and level premium limits and enforces a death benefit corridor.
What does CVAT stand for in life insurance?
CVAT stands for Cash Value Accumulation Test, one of two tests under IRC §7702 a policy must pass to qualify as life insurance for federal tax purposes.
What is GPT insurance?
GPT, or Guideline Premium Test, is the §7702 alternative to CVAT. It restricts total premiums paid into a policy and requires a minimum death-benefit-to-cash-value corridor, according to Investopedia.
Is face value the same as cash surrender value?
No. Face value refers to the death benefit payable at the insured’s passing, while cash surrender value is the amount the policyholder could receive if the policy were surrendered, a distinction that becomes especially relevant under CVAT’s cash value cap.
Can an insurer switch a policy from CVAT to GPT after issue?
No. The test is selected at issue and remains fixed for the life of the contract, as confirmed in IRS technical guidance on Section 7702 compliance.
This post is educational only and not financial, taxes, or legal advice. Consult qualified professionals before acting.
Recommended
Comments