
Why High Earners Need Alternative Assets in Their Portfolio

COMPLIANCE NOTE: For educational purposes only. Not financial, tax, or legal advice.
High earners often benefit from allocating a portion of capital to alternative assets because these assets can add non-correlated return drivers, inflation protection, and access to private-market opportunities that are underrepresented in public markets. Before you go further, here is the practical next step: confirm your tax-advantaged accounts are fully funded, verify you hold a liquid cushion sufficient for capital calls and living expenses, then schedule a due-diligence conversation with a qualified advisor.
Three quick credibility anchors worth noting up front:
FINRA classifies alternative investments as a distinct category with different risk, liquidity, and regulatory profiles than traditional securities, and flags suitability as a primary concern.
Institutional allocators, including large endowments and pension funds, have steadily increased private-market exposure over the past two decades, a trend that has filtered down to high-net-worth individual portfolios.
Goldman Sachs advises treating alternatives as complements to a diversified liquid portfolio, which should be considered only after maximizing tax-advantaged accounts and confirming adequate liquidity for capital calls and lock-ups.
Key Takeaways
High earners who allocate to alternative assets thoughtfully, after completing basic financial prerequisites, can access return drivers and diversification benefits that public markets alone do not provide.
Point | Details |
Sequencing comes first | Max tax-advantaged accounts and confirm a liquid cushion before committing any capital to alternatives. |
Concentration risk is the core problem | High earners’ income, equity, and savings often correlate; alternatives introduce different return drivers to reduce single-factor exposure. |
Manager selection drives outcomes | Performance dispersion between top and bottom managers in private markets is wide; due diligence is the primary risk-management tool. |
Tax complexity is real | K-1 delays, UBTI, pass-through income, and state tax treatment require specialized accounting; plan for extensions and estimated payments. |
The Infinite Banker as a complement | A properly structured dividend-paying whole life policy may serve as a liquidity tool alongside illiquid alternatives; policy loans accrue interest and reduce cash value and death benefit if unpaid; dividends are not guaranteed. |
Table of Contents
How to add alternatives to your portfolio without getting the sequence wrong
What to check before committing capital to any alternative manager
Tax and structural considerations U.S. high earners need to understand
What institutions know about alternatives that individual investors can apply
How Infinite Banking can complement an alternatives allocation
The Infinite Banker as a capital-efficiency complement to your alternatives strategy
Why conventional portfolios can leave high earners exposed
For high earners, a conventional stock-and-bond portfolio can leave major exposures that alternatives are specifically designed to address. The problem is not that public markets are bad. It is that a high earner’s total balance sheet often looks very different from the average investor’s, and a standard 60/40 allocation does not account for that difference.
Consider the concentration problem. A founder who draws a salary from her company, holds unvested equity in that same company, and keeps her retirement savings in a diversified index fund still has most of her financial life tied to one economic event: her company’s performance. If that company struggles, her salary, her equity, and potentially her business-related real estate all decline together. InvestmentNews notes that high earners face exactly this “concentration dilemma,” where income, business equity, and traditional investments frequently correlate, making alternatives a practical tool for introducing different return drivers.
There is also the correlation crunch to consider. During periods of acute market stress, stocks and bonds have historically moved together rather than offsetting each other, reducing the diversification benefit investors expected. A portfolio that looks balanced on paper can behave like a single-factor bet when conditions deteriorate.
The shrinking public market compounds this. The number of publicly listed U.S. companies declined roughly 40–50% over 25 years, and the median age at IPO has increased, meaning companies spend more of their high-growth years as private entities. Staying entirely in public markets means missing that growth phase by design.
High earners also face a tax drag that compounds over time. Ordinary income at the top marginal federal rate, combined with state income taxes in high-tax states, can erode returns from interest-bearing public instruments significantly. Some alternative structures offer different tax treatment, though the specifics depend heavily on structure and individual circumstances. For a deeper look at common planning pitfalls that high earners encounter before they reach the alternatives conversation, that context matters.
Which alternative assets exist and how they differ
The term “alternative assets” covers a broad range of investment types, each with distinct return drivers, liquidity profiles, and access requirements. Understanding the taxonomy is the first step toward deciding which categories belong in your portfolio.
Private equity and venture capital: Ownership stakes in private companies, either through buyout funds or early-stage venture. Lock-ups typically run 7–10 years. Potential for significant capital appreciation, but capital is illiquid and outcomes are highly manager-dependent. Generally requires accredited investor status; many institutional-quality funds require qualified purchaser status ($5 million in investments).
Private credit and direct lending: Loans to middle-market companies, often at floating rates with structural protections. Private credit has grown as a source of contractual cash flows partly because traditional bank lending to that segment has declined. Lock-ups vary from 3–7 years depending on the vehicle. Accredited investor status typically required.
Real assets and real estate: Direct property ownership, private real estate funds, and infrastructure. Provides potential inflation protection through rent escalation and asset appreciation. Lock-ups range from 3–10 years for private funds; REITs and real estate ETFs offer daily liquidity at the cost of higher correlation to public equities.
Hedge funds and liquid alternatives: Hedge funds use long/short, macro, arbitrage, and other strategies to generate returns with lower correlation to equities. Liquid alternatives replicate some of these strategies in mutual fund or ETF wrappers with daily liquidity. Hedge funds typically require qualified purchaser status and carry 1-and-10 or 2-and-20 fee structures.
Commodities: Exposure to physical goods (energy, metals, agriculture) through futures, ETFs, or commodity-linked notes. Historically useful as an inflation hedge. Highly liquid via ETFs; direct commodity ownership introduces storage and operational complexity.
Collectibles, art, and wine: Tangible assets with potential for appreciation and low correlation to financial markets. Valuation is subjective, markets are illiquid, and custody and insurance costs are real. Investopedia notes that alternatives like collectibles have higher complexity and longer effective lock-ups, making them most suitable for sophisticated investors.
Cryptocurrencies and digital assets: High volatility, 24/7 liquidity, and evolving regulatory treatment. Custody risk is material. Suitable only as a small, speculative allocation for investors who understand the technology and regulatory environment.
Interval funds and liquid alternatives: Registered vehicles that offer quarterly or monthly redemption windows, lower minimums, and access to private-market strategies without full illiquidity. NerdWallet observes that retail access to alternatives has expanded through these vehicles, though many private-market funds still require accreditation or high minimums.
What alternative assets can deliver for high earners
The core case for investing in alternative assets rests on four concrete portfolio-level benefits, each addressing a gap that public markets leave open.
Lower correlation and genuine diversification: Private equity, private credit, and real assets tend to move on different cycles than public stocks and bonds. Adding them can reduce portfolio volatility during public-market drawdowns, though correlation is never zero and can increase in severe liquidity crises.
Potential for return enhancement: JPMorgan Asset Management notes that private equity and direct lending can provide potential for outsized returns through alpha generation, operational improvements, and contractual cash flows less correlated with public markets. The key word is “potential” — outcomes depend heavily on manager selection.
Inflation protection via real assets: Real estate, infrastructure, and commodities have historically maintained purchasing power during inflationary periods because their cash flows and asset values tend to rise with prices. This is a structural feature, not a performance guarantee.
Contractual income from private credit: Unlike public bonds, private credit agreements often include structural protections, covenants, and floating-rate features that can provide more predictable income in rising-rate environments.
Access to private-stage growth: Because global alternative assets under management are expected to grow substantially through this decade, the opportunity set is expanding. High earners who qualify can access growth that occurs before companies reach public markets.
One important caveat: the benefits above are often manager-dependent. The dispersion between top-quartile and bottom-quartile managers in private equity and private credit is wide enough that a poor manager selection can eliminate the return premium entirely. Diversifying wealth through alternatives requires as much attention to manager quality as to asset class selection.
Key risks and trade-offs high earners must accept
Higher return potential in alternatives comes with structural costs that are non-trivial and, in some cases, irreversible once capital is committed. Understanding these trade-offs before allocating is not optional.
Illiquidity and lock-up risk: Capital committed to a private equity or private credit fund may be inaccessible for 7–10 years. Capital calls can arrive on short notice, requiring you to hold liquid reserves or face dilution or penalties.
Valuation difficulty: Unlike public securities, private assets are valued periodically using models rather than continuous market prices. This can mask volatility and make it harder to assess true portfolio risk at any given moment.
Fee drag: Management fees of 1–2% annually plus carried interest of 15–20% on profits are common in private funds. These fees can meaningfully reduce net returns, particularly in funds that do not consistently generate top-quartile performance.
Manager selection risk: The performance gap between top and bottom managers in alternatives is far wider than in public markets. Choosing the wrong manager is a primary risk, not a secondary one.
Regulatory and transparency gaps: Many alternative vehicles are exempt from full SEC registration, meaning disclosure requirements are lighter than for public funds. Investors rely more heavily on manager-provided information.
Operational and custody risk: Collectibles, digital assets, and direct real estate introduce custody, insurance, and operational complexity that public securities do not.
This approach limits timing risk and gives you direct experience with the operational realities of alternatives before scaling.*
Selling a rare collectible is not like selling a share of stock. Finding a buyer, authenticating the asset, and clearing a transaction can take months. That friction is the price of the low-correlation benefit.
How to add alternatives to your portfolio without getting the sequence wrong
The sequencing rule is straightforward: maximize tax-advantaged accounts, maintain a liquid cushion sufficient for capital calls and living expenses, then consider alternatives sized to your net worth, time horizon, and access to quality managers.
Prerequisites checklist before committing any capital to alternatives:
Tax-advantaged accounts (401(k), IRA, HSA, SEP-IRA, defined benefit plan where applicable) are fully funded for the year.
A liquid emergency and opportunity reserve of at least 12–24 months of expenses is in place, separate from any capital earmarked for alternative capital calls.
High-interest debt is resolved; moderate-rate debt has been assessed against expected alternative returns.
Investment objective is clearly defined: income, growth, inflation protection, or diversification.
You have access to quality managers or platforms, not just whatever is being marketed to you.
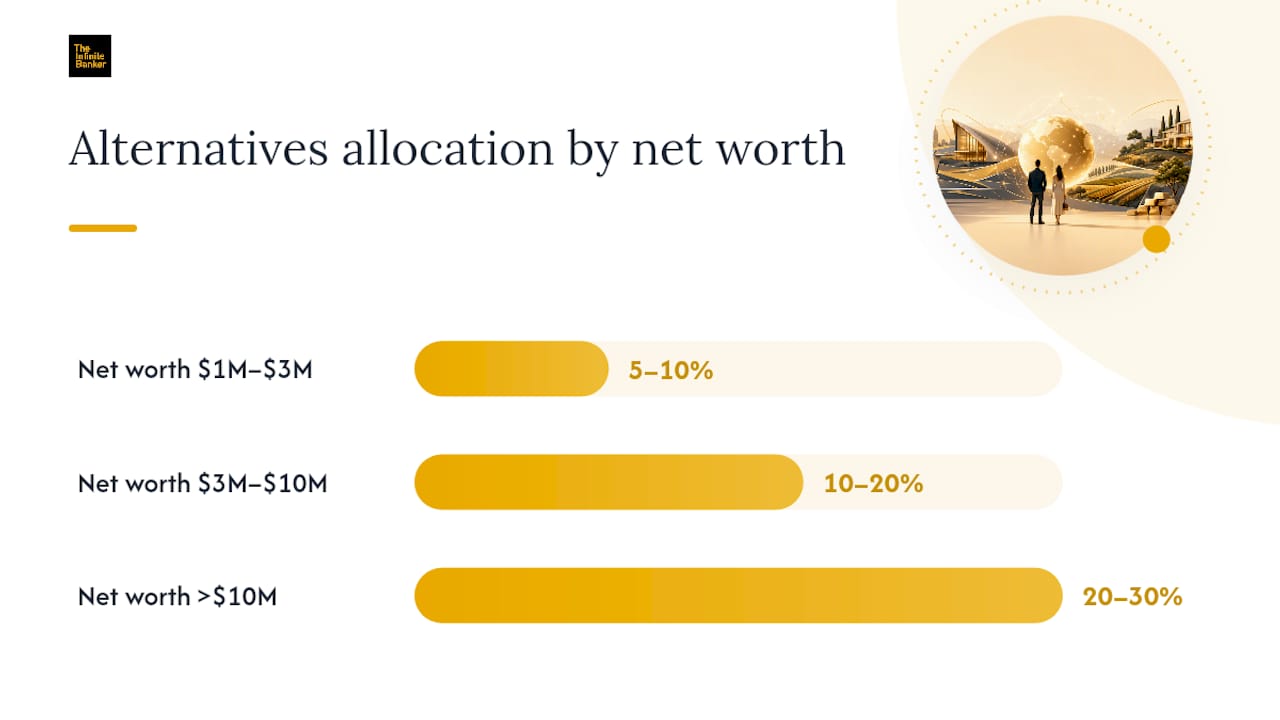
Illustrative allocation ranges (not prescriptive):
These ranges are illustrative only and depend on individual circumstances, risk tolerance, and liquidity needs. Consult a qualified advisor before acting.
Net worth $1M–$3M: 5–10% in alternatives, focused on liquid alternatives, REITs, or interval funds with lower minimums and shorter lock-ups.
Net worth $3M–$10M: 10–20%, with potential access to private credit funds, real estate private equity, and some hedge fund exposure.
Net worth above $10M: 20–30% or more, with access to institutional-quality private equity, co-investments, and direct deals.
Sequencing steps:
Complete the prerequisites checklist above.
Identify one or two asset categories that address a specific gap in your current portfolio (correlation, income, inflation).
Allocate a pilot position (5–10% of your alternatives budget) to a single manager or vehicle.
Ladder vintages over 2–3 years to reduce timing risk.
Evaluate co-investments or secondary purchases to manage J-curve effects in private equity.
Review annually and rebalance as liquidity events occur.
Goldman Sachs advises treating alternatives as complements to a diversified liquid portfolio, not as a replacement for financial fundamentals. That framing is worth keeping in mind throughout.
Pro Tip: Interval funds and evergreen structures offer quarterly or monthly redemption windows and lower minimums than traditional private funds. For high earners who are new to alternatives, these vehicles can provide meaningful exposure without a full 10-year lock-up commitment.
What vehicles give you access to alternative investments
Access to alternatives ranges from daily-liquidity ETFs to decade-long private fund commitments. The right vehicle depends on your net worth, accreditation status, time horizon, and appetite for complexity.
Private funds (limited partnerships): The traditional vehicle for private equity, private credit, and hedge funds. Highest potential return premium; longest lock-ups (5–10 years); highest minimums ($250,000–$5 million+); typically require qualified purchaser status. Access often comes through wealth managers or placement agents.
Co-investments: Direct investments alongside a fund manager in a specific deal, often at reduced or zero fees. Requires strong manager relationships and deal-level due diligence capability. Available to larger investors with established fund relationships.
Interval funds: Registered investment companies that invest in private-market assets but offer quarterly redemption windows. Lower minimums ($10,000–$25,000 typical); accessible to accredited investors; less liquidity than ETFs but more than traditional private funds.
Liquid alternatives (mutual funds and ETFs): Daily liquidity; no accreditation requirement; lower minimums. These replicate alternative strategies (long/short equity, managed futures, arbitrage) but typically with lower return potential and higher correlation to public markets than direct private-market exposure.
REITs (Real Estate Investment Trusts): Publicly traded or non-traded. Traded REITs offer daily liquidity and dividend income; non-traded REITs offer less liquidity but potentially lower correlation to public equities. No accreditation required for publicly traded REITs.
Crowdfunding platforms: Regulation Crowdfunding and Regulation A+ platforms have lowered minimums for real estate and private equity to $500–$5,000 in some cases. Accessible to non-accredited investors in some structures, though deal quality varies widely.
Separately managed accounts (SMAs): Custom portfolios managed by an alternative manager for a single investor. Highest transparency and tax efficiency; typically requires $1 million or more; available primarily to ultra-high-net-worth investors.
High earners often access top-quartile managers through established wealth management relationships, registered investment advisors with alternative platforms, or direct fund introductions. The vehicle matters, but manager quality matters more.
What to check before committing capital to any alternative manager
Due diligence is the primary driver of outcomes in alternatives, more so than in public markets where index funds can substitute for manager skill. Before committing capital, work through this checklist.
Manager and fund evaluation checklist:
Track record: Request audited performance data across multiple funds and vintages. Ask for both gross and net returns, and compare against a relevant benchmark.
Top-to-bottom quartile dispersion: Understand how the manager’s worst funds performed, not just the best. Wide dispersion signals high manager risk.
Fund economics: Confirm management fee, carried interest rate, preferred return (hurdle rate), and catch-up provisions. A 2-and-20 structure with no hurdle is materially different from a 1.5-and-15 with an 8% hurdle.
GP alignment: Ask what percentage of the fund the general partner has committed from their own capital. Low GP commitment is a misalignment signal.
Governance and reporting: Confirm the fund has an independent auditor, a qualified fund administrator, and quarterly reporting with clear valuation methodology.
Valuation policy: Ask how assets are valued between liquidity events. Mark-to-model valuations can smooth reported returns in ways that mask actual risk.
Liquidity terms and capital-call mechanics: Understand the notice period for capital calls, the consequences of missing a call, and the redemption process at fund end.
Custody and insurance: For funds holding physical assets (real estate, collectibles), confirm custody arrangements and insurance coverage.
Red flags:
Opaque or inconsistent reporting with no independent auditor.
Unusually complex fee waterfalls that make net return calculation difficult.
GP commitment below 1–2% of fund size.
Unclear or restrictive redemption mechanics.
Pressure to commit quickly without time for independent review.
Promised returns that exceed the asset class’s historical range.
Questions to ask a manager directly:
What is your sourcing edge, and how has it changed over the past five years?
How did your worst fund perform, and what did you learn from it?
What is your policy for valuing assets between liquidity events?
How do you handle a capital call if an LP cannot fund?
Who is your fund administrator and auditor?
Tax and structural considerations U.S. high earners need to understand
Tax treatment can materially affect net returns and timing; consult qualified tax counsel before committing to any alternative structure. The issues below are common enough that every high earner should understand them before allocating.
K-1 timing and complexity: Most private fund investments generate K-1s rather than 1099s. K-1s are frequently delayed past the standard April filing deadline, requiring extensions. They can also report income in categories (ordinary income, capital gains, Section 1231 gains) that interact differently with your tax situation.
Unrelated business taxable income (UBTI): If you hold alternative fund interests inside a tax-advantaged account (IRA, 401(k)), certain fund income may be classified as UBTI and taxed at the trust rate even inside the account. This is a common surprise for investors who assume tax-advantaged accounts shelter all income.
Depreciation and cost segregation for real estate: Direct real estate and real estate funds may generate significant depreciation deductions, including accelerated depreciation through cost segregation studies. These deductions can offset passive income but are subject to passive activity loss rules.
1031 exchanges: Real estate investors can defer capital gains by reinvesting proceeds into like-kind property under Section 1031. This deferral is powerful but has strict timing rules (45-day identification, 180-day closing) and does not apply to most other alternative asset classes.
Qualified Opportunity Funds (QOF/QOZ): Investors with realized capital gains can defer and potentially reduce those gains by investing in a Qualified Opportunity Fund within 180 days of the gain event. The tax benefit increases with holding period. This is a specialized structure that requires careful legal and tax guidance.
State tax implications: Some states do not conform to federal treatment of pass-through income, depreciation, or opportunity zone benefits. High earners in high-tax states (California, New York, New Jersey) face additional complexity.
Pass-through structures and estimated taxes: Income flowing through LLCs and partnerships may require quarterly estimated tax payments to avoid underpayment penalties. Fidelity notes that delayed K-1s and pass-through tax timing frequently require high earners to engage specialized tax accounting to avoid filing surprises.
Consult a CPA or tax attorney with direct experience in alternative investment structures before committing capital. The tax tail should not wag the investment dog, but ignoring it is expensive.
What institutions know about alternatives that individual investors can apply
Institutions use alternatives to add uncorrelated return streams and expand the investable universe beyond what public markets offer. That principle translates directly to high-earner portfolios, with some important adjustments for scale and liquidity.
The institutional case is straightforward: a meaningful share of economic value creation now happens before companies list publicly. Institutional investors shifted capital toward private markets to capture that value. InvestmentNews reports that private equity, private credit, and real assets have become core building blocks in high-net-worth portfolios, used for growth, income, diversification, and potential tax efficiency.
Fidelity’s alternative investment research confirms that alternatives can expand the investable universe and offer diversification, income generation, and inflation protection, while also introducing eligibility, liquidity, fee, and tax complexities. The institutional lesson is not to replicate an endowment portfolio wholesale. It is to apply the underlying principles selectively.
What high earners can replicate from institutional practice:
Long time horizons: Institutions commit capital for decades. High earners with a 10–20 year horizon can tolerate illiquidity in a portion of their portfolio and access the illiquidity premium.
Manager selection discipline: Institutions spend significant resources on manager due diligence. Individual investors should apply the same rigor, even if the process is shorter.
Vintage diversification: Committing capital across multiple years reduces the risk of entering at a single unfavorable market point.
Governance: Institutions maintain clear investment policy statements, rebalancing rules, and liquidity reserves. High earners benefit from the same structure, even informally.
The eligibility and sequencing rules discussed earlier apply here too. Institutional principles are sound; the sequencing and liquidity prerequisites are what make them safe to apply at the individual level. For a broader framework on long-term wealth accumulation strategies, the institutional lens is a useful starting point.
How Infinite Banking can complement an alternatives allocation
From my practice, I see Infinite Banking complement alternatives by providing controlled liquidity and policy-level capital efficiency that illiquid positions cannot offer on their own.
The practical scenario looks like this: a high earner has committed capital to a private equity fund with a 7-year lock-up. An unexpected capital call arrives, or a new co-investment opportunity appears, and selling the existing position is not an option. A properly structured dividend-paying whole life insurance policy can serve as a source of policy loans in that situation, providing access to cash without forcing a sale of an illiquid asset. Policy loans accrue interest and reduce the policy’s cash value and death benefit if unpaid, and dividends are not guaranteed. Policies can also lapse if premiums are not maintained. These are real costs, and they need to be weighed against the alternative of selling a position at a discount or missing a capital call.
What Infinite Banking does not do is replace alternatives. It does not generate private-equity-level returns, and it is not designed to. Its role is liquidity management and capital efficiency, sitting alongside an alternatives allocation rather than substituting for one. For high earners who want to understand the mechanics in detail, how Infinite Banking works is worth reviewing before any policy design conversation.
The Infinite Banker as a capital-efficiency complement to your alternatives strategy
For high earners who are already allocating to alternatives or preparing to do so, the liquidity gap between capital calls and available cash is a recurring operational challenge. The Infinite Banker works with entrepreneurs, real estate investors, and high-income earners to implement properly structured dividend-paying whole life insurance policies designed to address exactly that gap.
This is not a substitute for an alternatives allocation. It is a parallel structure designed to provide policy-loan access to capital without liquidating positions. Key distinctions from direct alternative investments:
Policy loans can be accessed without a redemption process or secondary market discount.
Premium schedules are predictable; capital calls from private funds are not.
Cash value growth is tied to the insurance carrier’s dividend performance, which is not guaranteed.
Policy loans accrue interest and reduce cash value and death benefit if unpaid.
The Infinite Banker’s approach is consulting-led: strategy sessions, policy design, and underwriting guidance tailored to your cash flow and capital-efficiency objectives. To discuss whether a properly structured policy may fit alongside your alternatives allocation, schedule a consult with an Authorized IBC Practitioner at The Infinite Banker.
Sources
The claims in this article draw on the following sources. Reviewing the originals is recommended before making any allocation decisions, and consulting qualified tax, legal, and financial advisors is necessary for structure-specific guidance.
Consult a qualified financial advisor, CPA, and attorney for tax or legal interpretation specific to your situation.
This post is educational only and not financial, tax, or legal advice. Consult qualified professionals before acting.
Recommended
Comments