
Infinite Banking as a Financing Tool for Real Estate Investors

COMPLIANCE NOTE: For educational purposes only. Not financial, tax, or legal advice.
Infinite Banking, implemented through a properly structured dividend-paying whole life insurance policy with policy loans, can be one of the most practical private financing tools for real estate investors who are willing to fund a policy over multiple years, prioritize liquidity control, and accept the trade-offs involved. This article covers only that strategy — whole life overfunding plus policy loans used as investor capital — and not conventional mortgages, hard money, or HELOCs.
When it tends to fit best: BRRRR down payments, rehab bridging, operating reserves, and deal closings where speed and credit flexibility matter more than lowest-cost financing.
Timing reality: Meaningful cash value for loans typically requires several years of consistent overfunding; some guidance suggests five to ten years depending on funding levels and policy design.
Risk reminder: Policy loans accrue interest, and unpaid loans reduce both cash value and death benefit. Underfunding or high loan balances can cause a policy to lapse.
Table of Contents
What does “Infinite Banking” actually mean for real estate investors?
Infinite Banking, as used here, refers to a specific strategy: overfunding a dividend-paying whole life insurance policy using paid-up additions (PUA) riders, then borrowing against the accumulated cash value through policy loans to fund real estate transactions. The insurer acts as the lender; your policy’s cash value serves as collateral.
This article applies exclusively to U.S.-based investors and U.S.-issued participating whole life policies. It does not cover term life insurance, universal life products, or any form of conventional bank or private-money lending.
The sections that follow cover mechanics, investor use cases, costs, policy design, risks, a worked example, and an implementation checklist. The Infinite Banker, led by Authorized IBC Practitioner Jib Hunt, is referenced throughout as a resource for investors pursuing this path.
How the mechanics of policy loans actually work
Whole life insurance builds cash value through two components: a guaranteed accumulation element and participating dividends credited by the insurer. Dividends are not certain and may vary year to year based on the insurer’s experience. When a PUA rider is added and overfunded, a larger portion of each premium goes directly to paid-up additions, which accelerates early cash-value growth and shortens the time before meaningful loans become available.
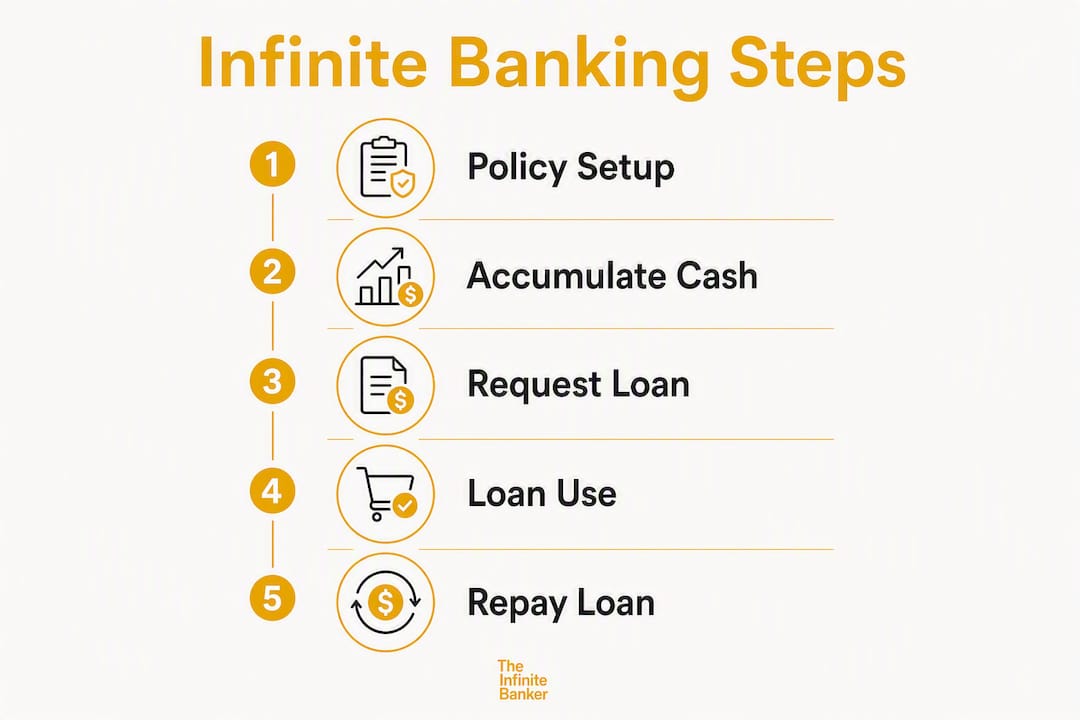
The step-by-step flow works like this:
Premium payment: You pay the base premium plus PUA contributions above the minimum required.
Cash value accumulation: The insurer credits guaranteed growth plus any declared dividends to your policy’s cash value account.
Loan request: You request a policy loan; the insurer lends from its own general account, using your cash value as collateral. No credit check is required.
Loan accounting: The loan appears as a separate loan account. Your cash value continues to earn dividends (though dividends are not certain) on the full unloaned balance, depending on the insurer’s dividend crediting method.
Loan interest: Interest accrues on the outstanding loan balance at the insurer’s published rate.
Repayment: You repay on your own schedule. Unpaid interest capitalizes into the loan balance, reducing net cash value and death benefit.
A simple mental model: policy → cash value → loan request → loan account → repayment cycle.
Pro Tip: Request a paid-up additions rider from the outset. Without it, early cash value grows slowly, and the policy may not produce usable loan capacity for a decade or more. With aggressive PUA funding, that window can shorten considerably.
Which investor use cases does Infinite Banking fit?
The strategy’s practical edge is liquidity speed and control, not necessarily the lowest cost of capital. For investors running repeatable deal cycles, that distinction matters.
BRRRR down payments. When you need to close fast on a distressed property, a policy loan can provide the down payment without a bank application or credit review. After refinancing the property, rental cash flow can repay the loan on a schedule you set.
Rehab bridge financing. Short-term rehab costs are a natural fit. You draw from the policy, complete the renovation, then repay from the refinance proceeds or sale. The policy continues accumulating value throughout.
Operating capital and reserves. Investors maintaining a reserve fund inside a policy rather than a savings account keep capital working while retaining access. This is particularly useful for landlords managing multiple properties with irregular expense timing.
Partner buyouts and distributions. When a partnership needs to buy out a departing partner, a policy loan can fund the transaction without triggering a bank underwriting process.
Where it is not ideal: if you need a large lump sum from day one, or if you cannot sustain multi-year premium funding, the strategy will not produce the capital you need when you need it. Alternatives such as taxable brokerage accounts or securities-based lending carry different trade-offs and may suit shorter time horizons better.
What does it cost and how long before you can borrow?
Accessible cash value typically requires multi-year overfunding. Published guidance commonly references that meaningful loan capacity typically requires multiple years of consistent overfunding, though aggressive PUA funding can compress that window.
Funding Approach | Annual Premium + PUA | Typical Loan Access Window |
Conservative | Lower base, minimal PUA | Multiple years; longer timelines typical |
Moderate | Base + moderate PUA | Multiple years; intermediate timelines typical |
Aggressive | Base + maximum PUA | Multiple years; shorter timelines possible with high funding and optimal design |
Ranges are illustrative. Actual timelines depend on insurer, policy design, and individual underwriting.
Key cost drivers to evaluate before committing:
Premium amount and cadence: Higher, consistent funding accelerates cash value.
PUA contributions: The primary lever for early liquidity.
Insurer dividend performance: Dividends are not certain and will affect actual cash value growth.
Commission and loading: Front-loaded costs reduce early cash value; ask for explicit disclosure.
Opportunity cost: Capital inside a policy is not deployed in other investments.
Loan interest applies to every dollar borrowed, regardless of dividend performance. Plan for it explicitly.
How to structure a policy for real estate use
Policy design choices — PUA rider size, target death benefit, and funding schedule — materially affect how quickly the policy produces usable capital. A poorly designed policy can take twice as long to reach the same loan capacity as a well-structured one.
Implementation checklist:
Define your capital goal: how much loan capacity do you need, and by when?
Decide your target annual overfunding amount, including PUA contributions.
Request a PUA rider and confirm the insurer allows maximum PUA funding relative to the base premium.
Request in-force illustrations showing loan projections under multiple dividend scenarios, including conservative ones.
Complete underwriting and any required medical exams.
Set loan terms, confirm the insurer’s loan interest rate policy, and document any collateral assignment requirements.
When selecting a carrier, prioritize participating whole life products with a consistent dividend history (noting dividends are not certain), a transparent loan-rate policy, clear loading disclosure, and accessible policy-service support.
Pro Tip: Insist that illustrations show both dividend-offset scenarios and downside dividend scenarios so you can see the breakpoints where loan interest exceeds dividend credits. Run illustrations conservatively — optimistic projections are the most common source of investor disappointment.
What are the real risks and trade-offs?
Infinite Banking offers liquidity control, but it comes with a long funding horizon and insurance costs that conventional financing does not carry. Understanding both sides is what separates a well-implemented strategy from an expensive mistake.
Core risks every investor must account for:
Loan interest accrual: Interest compounds on unpaid balances and reduces net policy value.
Reduced cash value and death benefit: Unpaid loans erode both, sometimes significantly.
Policy lapse risk: If loan balances grow too large relative to cash value, or if premiums lapse, the policy can terminate — triggering a taxable event on any gain.
Commission and loading drag: Early years carry the highest cost relative to cash value.
Opportunity cost: Capital committed to premiums is not available for direct property investment.
Tax nuances require professional review. A lapse or surrender of a policy with outstanding loans can create ordinary income tax liability on the gain. Consult a tax attorney and a fee-only financial planner before committing to a funding schedule.
A worked example: BRRRR down payment using a policy loan
A concrete example clarifies the trade-offs. The figures below are illustrative only; dividends are not certain, and actual results will vary.
Assumptions: $15,000 annual base premium, $10,000 annual PUA contribution ($25,000 total annual funding), 4% illustrative dividend rate (not certain), 5% policy loan interest rate.
Year | Cumulative Premiums Paid | Illustrative Cash Value | Available Loan (90% of CV) | Loan Interest (Year) | Illustrative Death Benefit |
1 | $25,000 | $18,000 | $16,200 | N/A | $500,000 |
3 | $75,000 | $62,000 | $55,800 | N/A | $510,000 |
5 | $125,000 | $112,000 | $100,800 | $5,040 (on $100,800) | $520,000 |
7 | $175,000 | $168,000 | $151,200 | $7,560 (on $151,200) | $530,000 |
All figures are illustrative. Dividends are not certain. Loan interest accrues on the outstanding balance and reduces net cash value and death benefit if unpaid.
By year five, this example policy may support a loan of roughly $100,000 — enough for a down payment on a mid-range investment property. The investor draws the loan, closes the deal, and repays from rental cash flow or refinance proceeds. The BRRRR strategy guide at The Infinite Banker walks through this cycle in more operational detail.
Step-by-step implementation from idea to funded policy
Follow these steps in sequence. Skipping underwriting or illustration review is where most implementation errors originate.
Clarify your investment goals, time horizon, and target loan capacity.
Run illustrations with at least two dividend scenarios (base and conservative) and confirm loan-account projections are included.
Select a carrier and agent — or work with The Infinite Banker — based on dividend history, loan rate transparency, and PUA flexibility.
Complete underwriting, including any medical exams required by the insurer.
Fund per your documented schedule; monitor loan activity and maintain a repayment plan tied to property cash flow.
Review the policy annually and adjust PUA contributions if your capital needs change.
Question to Ask Your Advisor | What a Good Answer Looks Like |
How will you design PUA contributions? | Specific ratio of PUA to base premium, with rationale |
Can you show loan-account illustrations? | Yes, with both dividend-offset and downside scenarios |
What are your commission and loading disclosures? | Full, written disclosure before application |
What happens if I miss a premium payment? | Clear explanation of grace period and lapse risk |
Can you illustrate a lapse scenario? | Yes, showing the tax and value consequences |
Red flags and vetting questions for any advisor
Short-term performance promises are the clearest warning sign. A well-structured policy takes years to produce meaningful capital; any advisor suggesting otherwise is either misinformed or misaligned with your interests.
Watch for these red flags:
Projections that show large loan capacity within the first one to two years without aggressive PUA funding.
No paid-up additions option offered or explained.
Illustrations that show only optimistic dividend scenarios.
Resistance to disclosing commission or loading costs in writing.
Pressure to sign quickly or fund before you have reviewed multiple illustrations.
Failure to show how unpaid loan interest affects the death benefit over time.
Document every answer you receive and request a second opinion from an independent fee-only financial planner before committing to a material funding schedule. The policy loan mistakes guide at The Infinite Banker covers the most common errors investors make after the policy is issued.
Key Takeaways
Infinite Banking can serve as a private financing tool for real estate investors when the policy is properly designed, consistently funded over multiple years, and managed with the same discipline applied to any debt obligation.
Point | Details |
Fit and timing | Best suited to investors with a multi-year funding horizon who prioritize liquidity control over lowest-cost capital. |
Cash value timeline | Meaningful loan capacity typically requires multiple years of funding; aggressive PUA design can compress that window depending on funding levels and policy design. |
Core costs | Loan interest, commission loading, and opportunity cost are the three primary drags to model before committing. |
Policy design matters | A PUA rider and conservative illustration scenarios are non-negotiable for investor-focused policy design. |
The Infinite Banker | Offers policy design, illustrations, underwriting guidance, and ongoing loan-account monitoring for investors implementing this strategy. |
Why most investors underestimate the design phase
The strategy’s mechanics are not complicated. What trips investors up is treating policy design as a formality rather than the most consequential decision in the entire process. A policy without a properly sized PUA rider, or one illustrated only at optimistic dividend assumptions, can underperform by years on the timeline to usable capital. That gap between expectation and reality is where most investor frustration originates.
The other underestimated factor is loan discipline. Borrowing from a policy without a documented repayment plan tied to property cash flow is the same error as taking on variable-rate debt with no exit strategy. The policy does not enforce repayment; you have to. Investors who treat that flexibility as a feature without building in structure tend to find loan balances compounding quietly until they create real policy stress.
The investors who use this strategy well are not the ones who found the best insurer or the lowest loan rate. They are the ones who ran conservative illustrations, funded consistently, and managed loan repayment with the same rigor they apply to their rental portfolios.
How The Infinite Banker supports real estate investors
Real estate investors who want to implement Infinite Banking need more than a policy — they need a design that matches their capital timeline, a carrier with transparent loan terms, and ongoing monitoring to keep loan balances from creating policy stress. The Infinite Banker provides exactly that: strategy sessions, policy design, underwriting guidance, and loan-account monitoring built around investor cash-flow cycles.
If you are evaluating whether this approach fits your portfolio, the clearest next step is a private consultation and a properly structured illustration. See who Infinite Banking is designed for and request a session with Jib Hunt, Authorized IBC Practitioner, to review your specific situation.
Useful sources and suggested reading
Life Insurance in BRRRR Strategy: A 2026 Investor Guide — The Infinite Banker
Whole Life Insurance in Your Real Estate Portfolio — The Infinite Banker
Private Lending With Whole Life Policy: A Practical Guide — The Infinite Banker
Infinite Banking: Using Life Insurance as a Source of Liquidity — NerdWallet
Rental Property Finance Guide for Landlords — Prop-Pocket (useful for modeling how policy loan repayment fits into property cash-flow underwriting)
For professional guidance, consult a fee-only financial planner, a tax attorney familiar with life insurance taxation, and an experienced participating whole life agent who can provide full commission and loading disclosure before you apply.
A note on the educational scope of this article
This post is educational only and not financial, tax, or legal advice. Consult qualified professionals before acting. Policy loans accrue interest; unpaid loans reduce cash value and death benefit, and policies can lapse if loan balances or underfunding create insufficient cash value to sustain coverage.
Recommended
Comments